How to Teach Kids About Money Without Turning Childhood Into a Business Lesson
Money is one of the most practical things children see every day — and one of the subjects families often avoid discussing.
They notice when groceries go into a cart, when a toy costs more than expected, when a parent says “not today,” or when a birthday gift comes with a card containing cash. They hear words like expensive, save, sale, allowance, and budget long before they truly understand what they mean.
That is why financial education does not need to begin with a bank account, investing app, or complicated spreadsheet.
It can begin with a much smaller goal: helping children understand that money involves choices.
A child does not need to know every detail of a family’s finances. In fact, they should not be asked to carry adult worries. But they can gradually learn that resources are limited, that people prioritize what matters, that waiting can be worthwhile, and that money can be used to care for themselves, others, and their community.
Those are not just financial skills. They are life skills.
Start with values, not fear
Financial education can easily become a source of anxiety when adults frame money only around scarcity, debt, or fear of making mistakes.
A healthier approach is to make money part of ordinary family life without making it the center of family life.
Children can learn that money is a tool. It helps people meet needs, make choices, plan ahead, share with others, and enjoy some of the things that make life pleasant.
That framework leaves room for the values each family wants to teach:
- security;
- generosity;
- patience;
- gratitude;
- responsibility;
- careful decision-making;
- enjoyment without excess.
The Consumer Financial Protection Bureau notes that young children build financial foundations through early skills such as counting, sorting, recognizing basic concepts of money and trading, and making choices. As they grow, children can begin managing small amounts of money or other resources to reach personal goals. CFPB: Financial Knowledge and Decision-Making Skills
The important word is gradually. Financial literacy is not one conversation. It is a series of small, age-appropriate experiences.
Teach needs, wants, and priorities without shame
One of the most useful ideas a child can learn is the difference between a need and a want.
Food, housing, clothing, health care, and safety are needs. A new toy, a branded water bottle, a video game, or a candy bar may be enjoyable wants.
This distinction should never be used to shame children for wanting something. Wanting is normal. The lesson is that people sometimes have to choose between several good things.
The CFPB’s youth education materials describe understanding needs and wants as a foundation for making spending decisions. Children can also learn to prioritize when they want more than one thing at the same time. CFPB: Budgeting for Needs and Wants
In ordinary life, that might sound like:
“We can choose one snack for the movie. Which one feels most worth it to you?”
Or:
“You have enough for this small toy today, or you can keep saving toward the bigger one you mentioned. What do you think?”
The goal is not to make a child responsible for adult bills. It is to let them practice choosing with a small, safe amount of responsibility.
Let children see the math behind everyday choices
Money can make abstract math feel useful.
At the grocery store, children can compare two package sizes. At a restaurant, they can estimate the total cost before the bill arrives. At a yard sale, they can decide whether an item is worth the price. At home, they can count cash from a birthday card or sort coins by value.
You do not need to turn every outing into a lesson. One question is enough:
- “Which is the better value for our family?”
- “Do you think we have enough for everyone?”
- “What would happen if we bought both?”
- “How much more would we need?”
- “Is this something we need now, or something we could plan for?”
This is where Math & Logic fits naturally. Children are not only practicing arithmetic. They are comparing options, estimating, noticing trade-offs, and explaining their reasoning.
Saving works best when it is connected to a real goal
“Save your money” can sound vague to a child. A visible goal makes the idea concrete.
A younger child may save toward a book, a small toy, a special outing, or supplies for a project. An older child may save for something bigger, such as sports equipment, a game, a class, or a trip with friends.
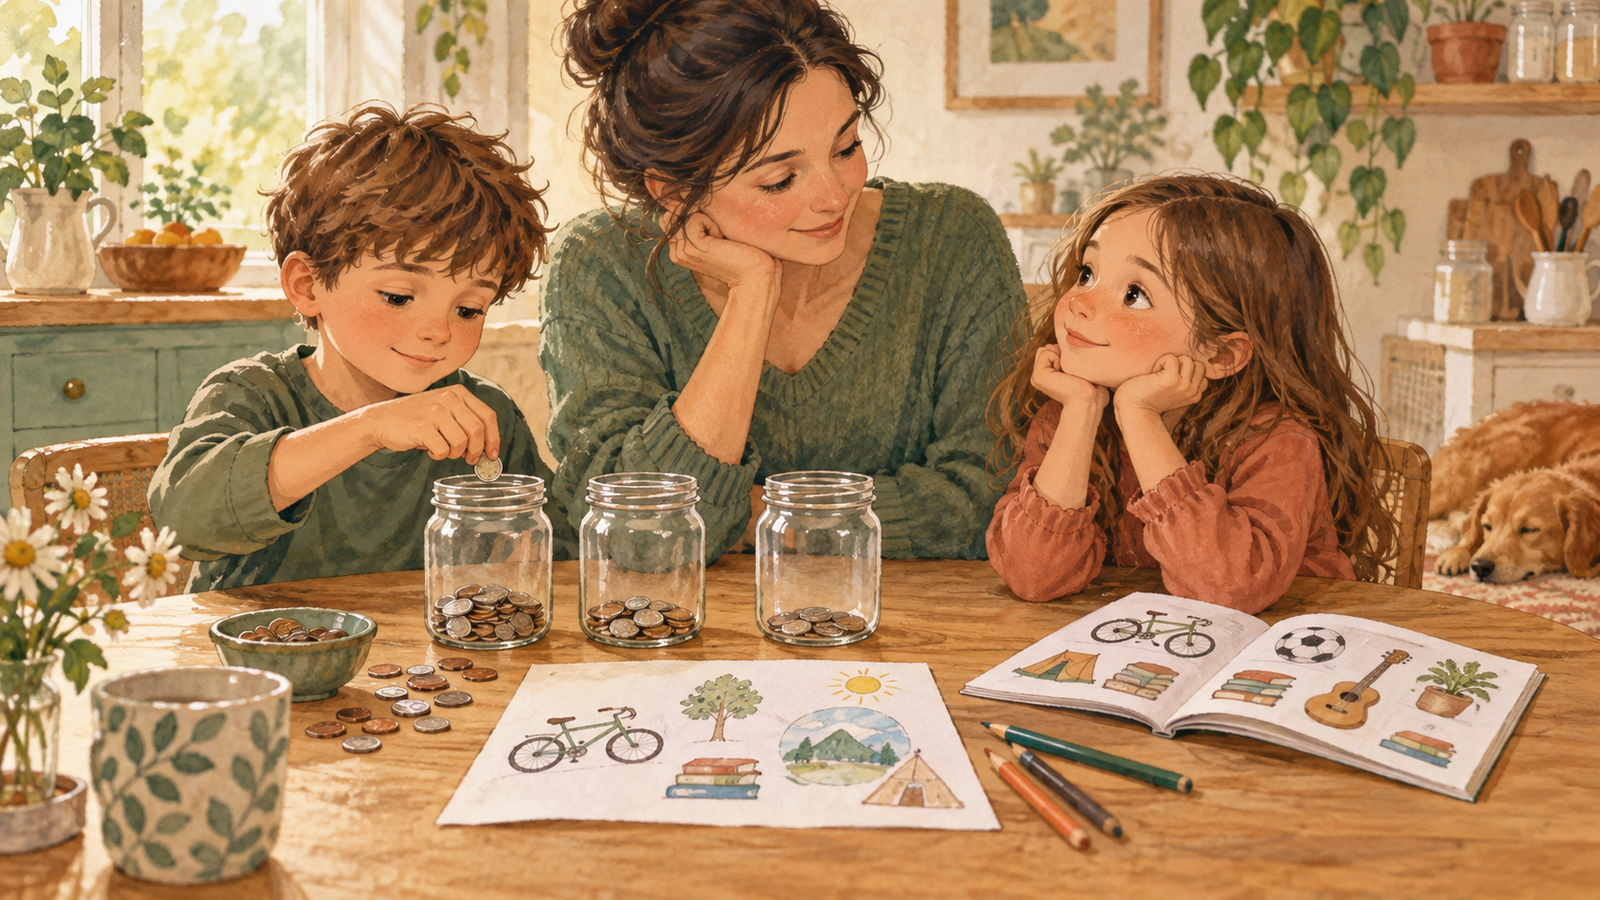
A clear jar, an envelope, a drawing of the goal, or a simple chart can make progress visible. The child does not need to save every dollar. They need to experience the satisfaction of making a plan and seeing it move forward.
The FDIC’s age-appropriate Money Smart curriculum includes goal setting, saving, spending decisions, needs and wants, and budgeting concepts from early childhood through high school. FDIC: Money Smart for Young People
The lesson is not that children should always delay enjoyment. It is that waiting can be an active choice when something matters more.
Allowance can help — but it is not required
Some families use an allowance. Others do not. Both approaches can support learning.
An allowance can give children a small, low-stakes chance to practice spending, saving, and making mistakes. But it is not the only way to teach financial responsibility, and basic family contributions should not always be treated as paid labor.
Children can help set the table, feed a pet, carry laundry, or put away groceries because they are part of a family. Separate paid opportunities can be offered occasionally for extra work that goes beyond regular shared responsibilities.
Other families may use birthday money, holiday gifts, a small budget for school supplies, or a pretend store game as the learning opportunity.
The method matters less than the conversation.
Teach generosity as part of the picture
A strong money conversation is not only about what children can buy or save for themselves.
Some families choose to include giving as one category whenever a child receives money. That could mean donating to a cause, helping choose groceries for a food drive, contributing to a classroom project, buying a thoughtful gift, or saving toward something kind for another person.
Giving should not be forced in a way that makes a child resentful. It is more meaningful when children can hear why a family chooses to share and have a small voice in where help goes.
The FDIC’s financial education resources include charitable giving alongside saving, spending, and other real-life money topics for older students. FDIC: Money Smart for Young People
This helps children see that money reflects values, not just purchasing power.
Help children become thoughtful consumers
Children are surrounded by messages designed to make them want things.
Advertisements, influencers, packaging, limited-edition products, and “everyone has one” conversations can make a purchase feel urgent. Older children especially benefit from learning to pause before buying.
Try asking:
- “What do you like about this?”
- “Would you still want it next week?”
- “What is the advertisement trying to make us feel?”
- “Are we comparing the same amount or the same quality?”
- “What else could this money do?”
This is not about making children suspicious of every purchase. It is about helping them recognize that wanting something and needing to buy it immediately are different things.
Keep adult financial stress off children’s shoulders
Children can understand simple, truthful explanations:
“That is not in our plan for today.”
“We are saving for something else right now.”
“We can choose one, not both.”
They do not need to hear every adult worry, debt concern, or financial conflict. Financial transparency should be appropriate to a child’s age and emotional capacity.
The point of involving children in small decisions is to build confidence, not responsibility for the household’s security.
If money is tight, a child can still learn values around creativity, sharing, planning, and contentment without being made to feel guilty for ordinary needs or wishes.
Age-by-age starting points
Ages 3–5: naming and sorting
At this age, focus on basic language:
- coins and bills are used to pay for things;
- people make choices;
- some things are needs and some are wants;
- saving means waiting for something later.
Use pretend play, sorting, counting, and short conversations.
Ages 6–9: goals and simple choices
Children can begin:
- comparing prices;
- saving toward one concrete goal;
- planning how to use a small amount of money;
- understanding that buying one thing may mean waiting for another;
- helping make a simple list before a store trip.
Ages 10–13: planning and comparison
Tweens can practice:
- tracking a small budget;
- comparing prices, quality, and value;
- thinking about advertising;
- saving for a longer-term goal;
- planning a small event or project within a set amount.
Teen years: growing independence
Teens may be ready to discuss:
- income from a job;
- recurring costs;
- banking basics;
- digital safety;
- saving goals;
- borrowing and the cost of credit.
The FDIC offers free parent and caregiver guides, organized by age group, for families who want more structured financial-education resources without a product recommendation. FDIC: Money Smart Resources
The real lesson is thoughtful choice
Children do not need to become little entrepreneurs. They need time to practice making choices, recovering from small mistakes, waiting for what matters, and seeing money as one tool among many in a good life.
A child who spends all of their birthday money on something they later regret has not failed. They have learned something in a safe environment.
A child who saves slowly toward a goal is learning patience.
A child who chooses a less expensive option so they can also give to someone else is learning values.
That is financial education worth carrying into adulthood.
This article is for general educational purposes and is not individualized financial, legal, tax, or investment advice.
Sources and further reading
- Consumer Financial Protection Bureau: Money as You Grow
- Consumer Financial Protection Bureau: Financial Knowledge and Decision-Making Skills
- Consumer Financial Protection Bureau: Budgeting for Needs and Wants
- Federal Deposit Insurance Corporation: Money Smart for Young People